
From £150K to £525M: What SME Owners Can Learn About Growth, Debt, Mezzanine Finance & Private Equity from Tamara Mellon
Hi, I’m Aby
Welcome to The Strategic Billion Dollar PEN, your weekly business strategy newsletter designed to equip SME business owners and entrepreneurs with the clarity, confidence, and competitive edge to grow and scale with purpose—successfully.
Want a smarter, stronger business?
Then it’s time to turn strategy into your superpower—the fuel behind every bold move, every sharp pivot, and every win that leaves your competition scrambling.
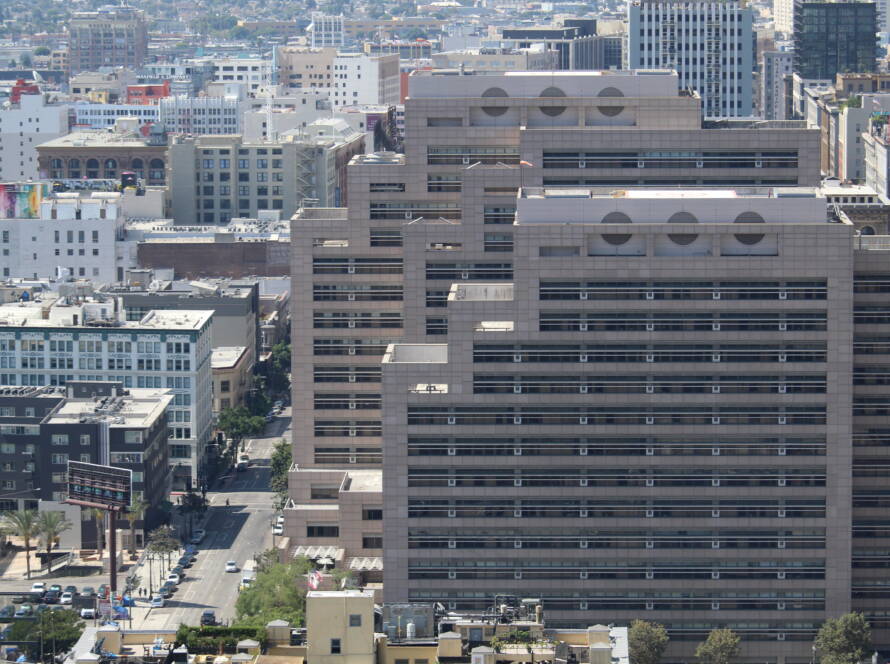
Our HERO image this week depicts A modern commercial skyline featuring a dominant central tower surrounded by supporting structures, symbolising how strategic funding, financial leverage, and capital allocation enable businesses to build scale, resilience, and sustainable growth over time.
Why Some Founders Lose Control Long Before They Sell
Introduction
In Week 3 of our Financing Series, we continue our exploration of mezzanine financing. This week, we examine how small and medium‑sized business (SMB) owners, founders and entrepreneurs can tap into another strategic financial growth lever that can help them build strong, growing, profitable 78910‑figure businesses with sustainable competitive advantage, through either organic or inorganic growth.
The process of growing a business through organic growth (internally through customer acquisition and operational expansion) or inorganic growth (externally through business acquisitions) will often involve the use of debt. Taking on debt means that the capital structure of the business must be carefully designed. The ratio of equity to debt must be optimised based on best practices and established industry standards to ensure lenders can be repaid and, in the worst‑case scenario of business failure, that creditors have a structured priority for recovering part of their investment.
For example, in the banking world, a company’s capital structure must demonstrate an acceptable debt‑to‑equity ratio before a bank will provide lending to support business growth or acquisitions. If this ratio falls outside acceptable ranges, lenders may be unwilling to provide financing.
As a result, SMB owners and entrepreneurs often seek ways to strengthen their capital structure and address lender concerns. One potential solution is mezzanine financing.
Mezzanine financing is a hybrid capital instrument positioned between senior secured debt and equity within the corporate capital stack. It behaves like debt by providing contractual interest payments while also incorporating equity‑like upside features, such as warrants, performance kickers, or equity conversion rights.
A simplified capital stack typically looks like this:
| Capital Layer | Risk / Return Profile |
| Common Equity | Highest Risk |
| Preferred Equity | Highest Return Potential |
| Mezzanine Financing | Hybrid Layer |
| Subordinated Debt / Notes | 12%–20%+ Returns |
| Second‑Lien Debt / Equity Warrants | Hybrid Characteristics |
| Unitranche / Junior Debt | Moderate Risk |
| Senior Secured Debt (Bank Debt) | Lower Risk |
| Revolving Credit Facility | Lowest Return |
Why Should Growth‑Focused SMB Owners Care About Mezzanine Financing?
1. Accessing Traditional Bank Lending
SMB owners seeking growth capital will often approach banks as their first source of funding. However, banks require evidence that the business generates sufficient cash flow to service debt while continuing to operate effectively on a day‑to‑day basis.
This means business owners must pay close attention to balance‑sheet requirements and ensure they maintain the right mix of debt and equity before approaching lenders.
If they do not, they must be prepared to demonstrate exactly how they plan to address the issue. Many business failures and collapsed acquisitions can be traced back to overlooking this fundamental banking requirement.
2. Unlocking Business Growth Opportunities
Sometimes, due to tighter lending standards or reduced senior debt availability, a business owner may struggle to access sufficient traditional financing.
In these situations, mezzanine financing can act as a bridge, helping fund growth opportunities while avoiding the need to bring in additional equity partners and dilute ownership.
For growth‑focused founders, mezzanine financing can provide the capital needed to move forward with expansion plans.
3. Supporting Acquisition Strategies
Mezzanine financing can also become a powerful tool within an acquisition strategy.
For SMB buyers and acquisition entrepreneurs seeking to purchase businesses in the lower‑middle market, particularly companies generating between £1 million and £10 million in annual profit, mezzanine financing can help bridge funding gaps and support transaction completion.
4. Additional Strategic Uses of Mezzanine Financing includes leveraged buyouts (LBOs) and recapitalisations & buyouts
Read also:
- How SMB owners can use equity financing to fund business growth.
- How SMB owners and entrepreneurs can use debt financing to fund business growth and acquisitions.
In this week’s Blueprint, we explore a memo titled:
Mezzanine Financing for SME Growth & Acquisition
The target audience includes SMB owners and buyers generating $1M–$10M in EBITDA, including:
- First‑time business buyers
- Serial acquirers purchasing their second, third, or fourth business
In our FLIGHT 78910™ SME Spotlight, we explore the Foundr interview with Tamara Mellon, co‑founder of Jimmy Choo, together with insights from her memoir In My Shoes. Her story highlights how the Jimmy Choo private‑equity era became defined by rapid corporate flipping, significant debt leverage, and repeated capital restructuring. The constant recycling of the company through multiple private‑equity firms ultimately contributed to the burnout and departure of Tamara Mellon from the business she helped create.
Finally, our Strategic Takeaway and Conclusion bring together the most important mezzanine‑financing lessons every entrepreneur, founder, business owner, and SMB leader should understand before pursuing business funding, growth initiatives, or acquisition opportunities.
BLUEPRINT
Building a £525M Brand: Lessons in Growth Capital, Private Equity and Founder Control
This week’s Blueprint is delivered in the form of a memo titled:
Mezzanine Financing for SME Growth & Acquisition
Target Audience
- First‑Time Buyers: Focus on equity conservation, bridging funding gaps without losing control, and understanding debt risk.
- Serial Acquirers (2nd to 4th Business): Focus on capital structure efficiency, speed of execution, acquisition scalability, and minimising personal dilution across multiple transactions.
This Blueprint also includes a practical case study and an action plan designed to help SMB buyers better understand what mezzanine financing is, how it works, and when it should be used.
Executive Summary & Audience Positioning
Presentation
To: SMB Owners & Buyers Generating $1M–$10M in Net Profit (EBITDA)
From: THE 2015B GROUP
For SMB owners generating between $1M and $10M in EBITDA, acquisition opportunities typically fall within the $5M–$50M Enterprise Value (EV) range.
Traditional bank financing (senior debt) generally funds between 3.0x and 4.0x EBITDA. However, many attractive businesses are valued between 5.5x and 7.0x EBITDA, creating a potential 1.5x–3.0x funding gap between available senior debt and the total acquisition price.
Mezzanine financing exists to fill this exact gap.
It sits between senior bank debt and common equity, allowing SMB owners and acquisition entrepreneurs to purchase larger, more profitable businesses without giving up majority ownership or bringing in equity partners who may demand board seats or control rights.
Presentation Roadmap
The following presentation framework provides a practical overview of how mezzanine financing supports SMB growth and acquisition strategies.
- Slide 1: The Acquisition Funding Dilemma ($1M–$10M EBITDA Space)
Understanding why traditional bank financing often falls short when acquiring high‑quality businesses and where funding gaps are created.
- Slide 2: What Is Mezzanine Financing and Where Does It Sit?
An introduction to mezzanine financing, its role within the capital stack, and how it bridges the gap between debt and equity.
- Slide 3: How Mezzanine Capital Works Mechanics & Cost Structures
Exploring subordinated debt, second‑lien facilities, warrants, conversion rights, interest structures, and expected investor returns.
- Slide 4: Strategic Value Why SMB Buyers Choose Mezzanine Financing
Examining how mezzanine financing can support growth, preserve ownership, improve capital efficiency, and accelerate acquisitions.
- Slide 5: Comparative Analysis Senior Debt vs. Mezzanine vs. Equity
A side‑by‑side comparison of risk, cost, control, ownership dilution, repayment obligations, and strategic implications.
- Slide 6: Real‑World SME Deal Breakdown (Acquisition Case Study)
A practical example illustrating how senior debt, mezzanine capital, and buyer equity work together to complete an acquisition.
- Slide 7: Risks, Covenants & Common Pitfalls to Avoid
Understanding deal structures, lender expectations, repayment risks, and common mistakes made by SMB buyers and entrepreneurs.
- Slide 8: Key Takeaways & Action Plan for SMB Buyers
A practical framework for determining whether mezzanine financing is suitable for your business, acquisition strategy, or growth plans.
Slide 1: The Acquisition Funding Dilemma ($1M–$10M EBITDA Space)
Headline:
How to Buy a $15M–$30M Business When the Bank Says “No” to the Full Amount
Key Audience Insights
- The Deal Size Reality: Quality SMEs generating $1M–$10M in EBITDA typically sell for 4.5x to 7.0x EBITDA.
- The Bank Funding Gap: Commercial banks will generally lend up to 3.0x–3.5x EBITDA through senior debt due to regulatory leverage limits and collateral requirements.
- The Equity Dilemma: Funding the remaining 30%–40% personally can significantly deplete liquid wealth or require bringing in private‑equity investors who may demand 30%–51%+ ownership, board representation, and varying degrees of control.
SMB Takeaway
“For SMB owners generating up to $10M in profit, the lower‑middle market presents significant acquisition opportunities. Whether acquiring your first business or rolling up your third or fourth competitor, senior lenders will often only take you part of the way. Mezzanine financing can serve as the financial bridge that allows you to acquire larger, cash‑flow‑rich businesses while retaining 80%–90%+ ownership.”
Slide 2: What Is Mezzanine Financing & Where Does It Sit?
Headline:
The Flexible Hybrid Layer Between Senior Debt and Equity
Core Concepts
- Position in the Capital Stack: Mezzanine financing sits below senior debt and above common equity in the capital structure.
- Unsecured or Second‑Lien Structure: Mezzanine lenders rely primarily on the business’s future cash flow and earnings strength rather than hard collateral such as equipment or property.
- Hybrid Characteristics:
- Behaves Like Debt: Provides contractual interest payments through cash or accrued interest.
- Behaves Like Equity: Offers investors additional return potential through warrants, equity participation rights, or conversion features.
SMB Takeaway
“Think of mezzanine financing as patient, cash‑flow‑based capital. Senior lenders focus on what they can liquidate if things go wrong. Mezzanine lenders focus on the quality of your earnings, the strength of your cash flow, and the future growth potential of the business.”
Slide 3: How Mezzanine Capital Works — Mechanics & Cost Structure
Headline:
Understanding the Total Cost of Capital (12%–18% All‑In IRR)
Breakdown of Pricing Components
| Component | Typical Range | How It Works | SMB Benefit |
| Cash Coupon | 7%–10% | Paid monthly or quarterly | Lower cash burden than many short‑term bridge facilities |
| Payment‑in‑Kind (PIK) | 2%–5% | Accrues into principal and is repaid at maturity | Preserves working capital during growth and integration periods |
| Equity Warrants / Equity Kicker | 1%–5% | Small equity participation at exit | Reduces the need for significant ownership dilution |
| Total All‑In Return (IRR) | 12%–18% | Combination of cash interest, PIK, and equity upside | Often less expensive than traditional private‑equity capital, which frequently targets 25%+ returns |
Key Terms SMB Owners Should Understand
Bullet Maturity
Principal is repaid as a lump sum at maturity, typically after five to seven years. This allows management to deploy cash flow into growth, acquisitions, or debt reduction during the investment period.
Subordination & Intercreditor Agreements (ICA)
A formal agreement that gives senior lenders payment priority while mezzanine lenders agree to subordinate their position and accept certain standstill provisions in the event of default.
SMB Takeaway
“Mezzanine financing is not cheap capital, but it can be significantly cheaper than giving away large portions of your business. When used correctly, it helps bridge acquisition funding gaps, preserve ownership, and accelerate growth without immediately introducing new equity partners.”
Section 4: Strategic Value — Why SMB Buyers Choose Mezzanine Financing
Headline:
Bridging the Funding Gap Without Sacrificing Control or Growth.
Perspective A: First‑Time Business Buyers
Preserve Personal Wealth
Mezzanine financing helps bridge the acquisition funding gap without requiring founders to exhaust personal savings, liquidate investments, or mortgage personal assets.
Institutional Validation
Mezzanine lenders typically conduct extensive financial, operational, and commercial due diligence. Their willingness to participate often provides additional validation of the target company’s cash‑flow quality and growth prospects.
Maintain Operational Control
Unlike private equity investors, mezzanine lenders generally do not seek operational control, board seats, or direct involvement in day‑to‑day management decisions.
SMB Takeaway
“For first‑time buyers, mezzanine financing can provide access to larger acquisitions without sacrificing ownership, control, or personal financial security.”
Perspective B: Serial Acquirers (2nd, 3rd, or 4th Acquisition)
Speed to Close
Mezzanine funding can often be arranged more quickly than raising new equity syndications, helping buyers move faster on attractive acquisition opportunities.
Portfolio Leverage
It allows serial acquirers to pursue multiple acquisition opportunities simultaneously without exhausting their available equity capital.
Tax Efficiency
Both cash interest and Payment‑in‑Kind (PIK) interest are often tax‑deductible, subject to local tax regulations, creating an ongoing tax shield for the business.
SMB Takeaway
“For experienced acquirers, mezzanine financing is often a strategic scaling tool that increases purchasing capacity while improving capital efficiency.”
Slide 5: Comparative Analysis — Choosing the Right Capital Structure
Headline:
Comparing Funding Sources Across Cost, Dilution, and Control.
| Metric | Senior Bank Debt | Mezzanine Financing | Private Equity / Equity Partners |
| Cost of Capital (IRR) | Lowest (6%–9%) | Moderate (12%–18%) | Highest (20%–30%+) |
| Collateral Required | High (first lien on assets) | Minimal (subordinated, cash‑flow based) | None |
| Equity Dilution | 0% | Very Low (typically 1%–5% warrants) | High (30%–51%+ ownership) |
| Board & Operational Control | None (financial covenants only) | Minimal (typically observer rights in distress situations) | Significant control, board influence, and voting rights |
| Repayment Structure | Amortising principal repayments | Interest‑only with PIK and bullet maturity | Typically realised through an eventual sale, recapitalisation, or exit event |
SMB Takeaway
“Senior debt is the cheapest capital, but it has borrowing limits. Equity is often the most expensive capital because it permanently dilutes ownership. Mezzanine financing occupies the middle ground, providing growth capital while preserving founder control.”
Slide 6: Real‑World SME Deal Breakdown (Acquisition Case Study)
Scenario
Acquiring a $20M Enterprise Value business generating $4M in EBITDA (5.0x EV / EBITDA multiple).
Deal Financing Structure
| Funding Source | Amount | Percentage |
| Senior Bank Debt (3.0x EBITDA) | $12,000,000 | 60% |
| Mezzanine Financing (1.0x EBITDA) | $4,000,000 | 20% |
| Buyer / Sponsor Equity | $4,000,000 | 20% |
| Total Enterprise Value | $20,000,000 | 100% |
The Outcome
Without mezzanine financing, the buyer would likely need approximately $8,000,000 of equity (40%) to complete the acquisition.
By introducing mezzanine financing, the buyer’s equity requirement falls to $4,000,000 (20%), significantly improving return on equity (ROE) while preserving majority ownership and control.
SMB Takeaway
“Mezzanine financing allows acquisition entrepreneurs to purchase larger businesses using less equity, preserving capital for future growth and additional acquisitions while maintaining ownership control.”
Slide 7: Risks, Covenants & Common Pitfalls to Avoid
Headline:
Understanding the Risks Before You Use Mezzanine Financing.
While mezzanine financing can be a powerful growth and acquisition tool, SMB owners must understand the associated risks and structure transactions carefully.
1. The PIK Snowball Effect
Risk
Because Payment‑in‑Kind (PIK) interest accrues and compounds into the outstanding debt balance, total debt can grow significantly over time if not actively managed.
Mitigation
Ensure that post‑acquisition cash flows and expected synergies support partial debt repayments, refinancing strategies, or recapitalisation opportunities within the first three to five years.
SMB Takeaway“PIK financing preserves cash flow today, but if left unmanaged it can create a much larger repayment obligation in the future.”
2. Leverage Over‑Extension
Risk
Combining 3.5x Senior Debt with 1.5x Mezzanine Financing creates approximately 5.0x total leverage. A relatively small decline in EBITDA can rapidly compress debt‑coverage ratios and increase financial stress.
Mitigation
Maintain a minimum Debt Service Coverage Ratio (DSCR) of 1.25x to 1.50x under stress‑tested scenarios to ensure the business can withstand economic downturns or operational disruptions.
SMB Takeaway
“The goal is not to maximise leverage. The goal is to maximise sustainable leverage.”
3. Intercreditor Friction
Risk
Disputes can arise between senior lenders and mezzanine providers during covenant breaches, restructurings, or periods of financial distress.
Mitigation
Work with experienced legal and financial advisers to establish clear Intercreditor Agreements (ICAs), standstill periods, cure rights, and dispute‑resolution mechanisms before closing the transaction.
SMB Takeaway
“The best time to solve lender disputes is before they exist.”
Section 8: Key Takeaways & Action Plan for SMB Buyers
Slide 8: Key Takeaways & Action Plan for SMB Buyers
Preparing Your Business to Use Mezzanine Capital Effectively.
Acquisition Action Plan
Step 1: Audit Earnings Quality
Review and validate EBITDA quality, remove one‑off adjustments, and calculate available debt capacity.
Why It Matters:
Mezzanine lenders primarily underwrite the predictability and sustainability of cash flow.
Step 2: Target the Right Acquisition Size
Focus on acquisition opportunities within the $5M–$30M Enterprise Value range, where mezzanine financing is most commonly used to bridge funding gaps.
Why It Matters:
This is often where traditional senior lenders begin reaching their leverage limits.
Step 3: Build Capital Relationships Early
Establish relationships with:
- Private credit funds
- Family offices
- Mezzanine lenders
- Alternative capital providers
before signing Letters of Intent (LOIs).
Why It Matters:
Capital providers prefer to develop relationships before financing opportunities arise.
Step 4: Structure the Capital Stack
A typical acquisition funding structure might include:
- Senior Debt: 60%
- Mezzanine Financing: 20%
- Buyer Equity: 20%
Why It Matters:
A well‑structured capital stack balances growth, risk, ownership preservation, and lender requirements.
Key Action Points for SMB Buyers
- Audit EBITDA Quality
Mezzanine providers focus heavily on earnings quality and cash‑flow predictability. Ensure financial reporting is robust, transparent, and ideally externally verified.
- Right‑Size the Mezzanine Layer
As a general guideline, keep mezzanine financing between 10% and 25% of total transaction value. This often provides optimal leverage without excessively increasing financial risk.
- Engage Private Credit Providers Early
Begin building relationships with lenders well before acquisition opportunities emerge. Funding conversations are often more successful when trust already exists.
Blueprint Takeaway
“Mezzanine financing is most powerful when used as a bridge, not a crutch. The strongest SMB acquirers use it to close funding gaps, preserve ownership, and accelerate growth while maintaining a disciplined capital structure.”
Flight 78910™ SME Spotlight: Tamara Mellon
WATCH Video Feature: She Went From $0 to $1.2 Billion Selling Shoes | Tamara Mellon
From a £150,000 family loan to building one of the world’s most recognised luxury footwear brands, Tamara Mellon helped transform Jimmy Choo from a small London shoe business into a global fashion powerhouse She co-founded Jimmy Choo in 1996 after identifying the commercial potential of designer Jimmy Choo’s craftsmanship while working as an accessories editor at British Vogue. Financing the venture with a £150,000 loan from her father, Mellon focused on operations, manufacturing, branding and distribution while Choo concentrated on design and shoemaking.
The brand became synonymous with celebrity culture throughout the late 1990s and 2000s. Worn by Hollywood stars and made famous through its association with Sex and the City, Jimmy Choo evolved into one of the most desirable luxury footwear brands in the world. Mellon’s understanding of celebrity endorsement and brand positioning helped elevate the company far beyond traditional luxury retail.
By 2011, Jimmy Choo was sold to Labelux in a deal valued at approximately £525.5 million, following several ownership changes involving private equity investors and strategic acquisitions.
The Real SME Lesson: Finance vs Product
Beyond the glamour of luxury fashion, the Jimmy Choo story is a valuable case study in:
- Leveraged buyouts (LBOs)
- Private equity investment cycles
- Debt-funded expansion
- Growth through multiple ownership structures
- Founder influence versus investor influence
- Corporate restructuring and turnaround strategies
Throughout various ownership transitions, Mellon became increasingly vocal about the tension between creative brand building and private equity’s focus on short-term financial returns.
Reflecting on these experiences, she argued that many financial investors were driven by relatively short investment horizons and exit strategies rather than long-term brand development. Mellon observed that significant effort often went into preparing businesses for sale rather than investing in product innovation, customer experience and long-term infrastructure.
Her criticism highlights a challenge faced by many founders:
When financial engineering becomes the priority, product excellence can become secondary.
Flight 78910™ Takeaway
Many entrepreneurs believe scaling a business is the finish line.
Tamara Mellon’s journey demonstrates that scaling is only one phase. Ownership structure, debt levels, investor objectives and governance can ultimately shape the future of a company just as much as the product itself.
For SME owners, the lesson is clear:
Growth capital can accelerate growth. Private equity can create value. But founders must understand the long-term implications of who controls the capital and who controls the vision.
Jimmy Choo was not merely a luxury fashion success story.
It was a masterclass in branding, capital raising, private equity transactions, restructuring, and the ongoing tension between creative entrepreneurship and financial optimisation.
Apply the Playbook →
Every Blueprint and Spotlight in this newsletter is a strategic lever.
Which one will you use to build a stronger, more competitive SME?
Strategic Takeaway
The objective for SME owners, entrepreneurs and business buyers is not simply to secure mezzanine financing. The real objective is to understand when mezzanine capital is appropriate, how it works within a broader capital structure, and the risks and obligations it introduces.
Used correctly, mezzanine financing can help bridge funding gaps, support acquisitions, accelerate growth and preserve ownership. Used poorly, it can create significant refinancing pressure, governance challenges and long-term value erosion.
What SME Owners Need to Understand
1. Implementation Strategy
Before considering mezzanine capital, business owners should understand:
- When mezzanine financing is appropriate
- Which businesses are suitable candidates
- How mezzanine debt fits between senior debt and equity
- How to structure repayment and exit strategies
- How to maintain adequate debt service coverage and cash flow resilience
2. Mezzanine Financing Framework
A successful mezzanine structure typically includes several key components:
- Cash Coupon (Current Yield)
The cash interest paid periodically to lenders. - Payment-In-Kind (PIK) Interest
Interest that accrues and is added to the principal balance rather than paid in cash. - Equity Kickers / Warrants
Rights granted to lenders to participate in future equity upside. - Target Investor Return (IRR)
The overall return investors expect to achieve from the financing arrangement.
3. Legal and Intercreditor Requirements
Business owners should fully understand:
- Intercreditor agreements
- Priority of claims
- Covenant restrictions
- Default provisions
- Security and enforcement rights
- Debt-to-equity conversion provisions
4. Borrower Benefits vs Borrower Risks
| Potential Benefits | Potential Risks |
| Preserves founder ownership | Higher cost of capital |
| Less dilutive than raising equity | Refinancing risk |
| Flexible growth capital | PIK interest accumulation |
| Tax-deductible interest in many jurisdictions | Complex legal structures |
| Supports acquisitions and expansion | Potential loss of control during restructuring |
5. Strategic Benefits
- Capital Cost Optimisation
Often less expensive than issuing significant new equity while providing additional growth capital.
- Reduced Ownership Dilution
Founders and existing shareholders retain greater participation in future value creation.
- Growth Flexibility
Can support acquisitions, expansion projects, management buyouts and succession transactions.
- Potential Tax Advantages
Interest payments may offer tax benefits where permitted under applicable regulations.
6. Key Financial and Governance Risks
- Refinancing Risk
PIK interest can significantly increase debt balances over time, creating future refinancing challenges.
- Debt Service Pressure
Interest obligations can strain cash flow during economic downturns or operational disruptions.
- Control Risk
In distressed situations, lenders may obtain increased governance rights, conversion rights or ownership interests.
- Exit Timing Risk
Investor return expectations may influence future strategic decisions, including sale timing.
7. Global Market Trends and Key Players
SME owners should understand:
- Changes in interest rates and private credit markets
- Current mezzanine market conditions
- Institutional lender participation
- Private credit fund activity
- Family office involvement
- Direct lending trends
- Sector-specific financing preferences
Conclusion
Mezzanine financing is another tool in the strategic toolbox of SME owners, founders and entrepreneurs who have the vision to accelerate growth through external capital rather than relying solely on organic growth and internally generated cash flow.
When used appropriately, mezzanine financing can be an effective solution for:
- Acquisitions and Buyouts
- Business Expansion.
- Recapitalisations and Restructurings.
Whether mezzanine financing is an optional source of growth capital, a necessary funding solution or a transaction-driven requirement, business owners must fully understand the structural, financial and governance factors that determine whether it becomes a successful growth tool or an expensive debt burden.
As outlined in the Strategic Takeaway section, success depends not simply on securing the funding, but on understanding every component that supports the financing structure, including pricing mechanisms, covenants, investor expectations, repayment obligations and exit requirements.
Cash Flow Remains the Holy Grail
As with all forms of business finance, cash flow remains the foundation upon which lending decisions are made.
Regardless of how sophisticated a capital structure becomes, lenders ultimately focus on one question:
Can the business consistently generate sufficient cash flow to service its obligations while continuing to grow?
For this reason, growth-oriented business owners must understand both the opportunities and risks associated with mezzanine financing before introducing it into their capital structure.
As demonstrated in this week’s FLIGHT 78910™ SME Spotlight featuring Tamara Mellon, even businesses with strong brands, significant investor backing and international growth can encounter challenges when cash flow struggles to keep pace with debt obligations, investor expectations, refinancing requirements and strict performance targets.
The lesson is straightforward: as leverage increases, so do the demands placed on the business.
Debt Versus Equity
One of the key attractions of mezzanine financing is its ability to reduce ownership dilution and allow founders to retain greater control and participation in future value creation.
However, avoiding dilution is not always the best outcome.
In certain situations, accepting a degree of equity dilution may create a stronger and more sustainable business than assuming additional debt obligations and refinancing risk.
The critical question is not whether debt is better than equity.
The critical question is:
Why is this financing structure being used, and can the business realistically support it over the long term?
Mezzanine financing is not a growth strategy.
It is a financing tool designed to support a growth strategy.
The most successful entrepreneurs understand where mezzanine capital fits within their capital stack, how it affects cash flow, what obligations it creates and how it aligns with their long-term objectives.
When used appropriately, mezzanine financing can be a powerful catalyst for growth. When misunderstood or poorly structured, it can become a significant source of financial and operational pressure.
Ultimately, mezzanine financing is simply another strategic lever available to business owners seeking to build a strong, growing and profitable 78910™ business with a sustainable competitive advantage.
References
Subscribe for weekly strategy your fellow SMEs are already using to strengthen their competitive edge.
Related Posts:
- How to Buy a Business Without Millions: The SMB Acquisition Funding Blueprint – The2015B Group
- Equity Financing for SMBs: How to Raise Capital Without Losing Control – The2015B Group
Until next week—
Set bold strategy. Set big targets. Take massive action. Measure what matters.
About the Author
Aby Rufus
Business Investor Strategy Expert Entrepreneur with an MBA in Strategic Planning—offering billion-dollar strategic solutions for SMEs.