
Vendor Financing Explained: How SME Owners Use Seller Financing to Buy and Grow 7- 8- 9- & 10-Figure Businesses
Hi, I’m Aby
Welcome to The Strategic Billion Dollar PEN, your weekly business strategy newsletter designed to equip SME business owners and entrepreneurs with the clarity, confidence, and competitive edge to grow and scale with purpose—successfully.
Want a smarter, stronger business?
Then it’s time to turn strategy into your superpower—the fuel behind every bold move, every sharp pivot, and every win that leaves your competition scrambling.
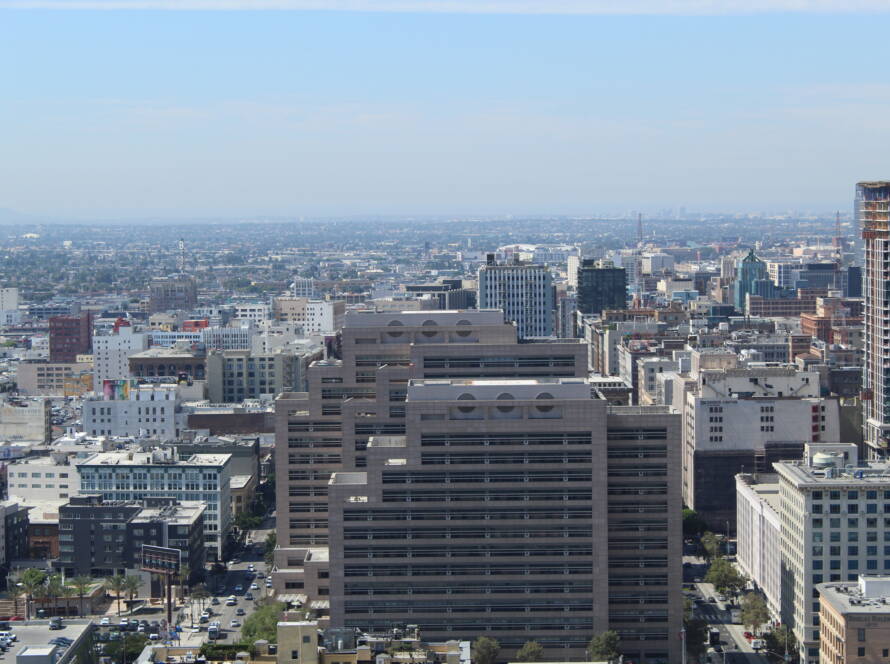
Our HERO image this week depicts A modern commercial skyline featuring a dominant central tower surrounded by supporting structures, symbolising how strategic funding, financial leverage, and capital allocation enable businesses to build scale, resilience, and sustainable growth over time.
The Business Seller Knows More Than You. Make Them Share the Risk.
Introduction
In Week 4 of our Financing Series, we continue our exploration of Vendor Financing (Seller Financing) and how it can be used as a powerful strategic growth lever for SME owners, entrepreneurs, and acquisition-minded business leaders.
This series examines how different financing tools can help business owners build stronger, growing, and more profitable businesses. This week, we focus on how vendor financing can help buyers acquire existing businesses, preserve capital, align incentives, and accelerate growth through acquisition.
For entrepreneurs seeking to build 7-, 8-, 9-, and 10-figure businesses, acquisition can often provide a faster route to growth than building entirely from scratch. Instead of spending years developing customers, revenue streams, operational systems, market credibility, and cash flow, business buyers can acquire assets that are already producing results.
Vendor financing is one of the key mechanisms that can make this possible.
What Is Vendor Financing?
Vendor financing, often referred to as Seller Financing, a Seller Note, or a Vendor Take-Back (VTB), is a hybrid financing instrument in which the seller provides part of the funding needed to complete a business acquisition.
Rather than receiving 100% of the purchase price at closing, the seller agrees to accept a portion of the proceeds over a defined period through a promissory note issued by the buyer or acquired business.
In effect, the seller becomes part lender and part partner in helping facilitate the transaction.
For buyers, vendor financing can reduce the amount of upfront capital required to complete an acquisition. For sellers, it can increase transaction certainty, broaden the pool of potential buyers, and support higher overall valuations.
Why Vendor Financing Matters for Business Buyers
For first-time business buyers, acquiring an established business through vendor financing can significantly reduce many of the challenges commonly faced by start-ups.
Rather than beginning with:
- No customers
- Limited sales
- Uncertain market demand
- Cash-flow pressures
- Difficulty securing finance
the buyer acquires an operating business with existing customers, established revenue streams, supplier relationships, systems, processes, and market presence.
In many cases, acquisitions allow buyers to accelerate years of business development and gain immediate access to cash flow that would otherwise take considerable time, capital, and effort to build organically.
Given the well-documented challenges faced by many start-up businesses during their early years, acquiring an established operation can provide a more predictable platform for growth.
For more experienced buyers pursuing a second, third, or fourth acquisition, vendor financing can become an important tool for scaling through acquisition.
Instead of relying solely on organic growth, business buyers can acquire:
- Customers
- Revenue
- Market share
- Intellectual property
- Strategic capabilities
- Distribution channels
- Talent and expertise
When combined with a disciplined acquisition strategy, vendor financing can help entrepreneurial business owners build stronger, growing, profitable businesses with sustainable competitive advantage.
Whether through horizontal acquisitions, vertical integration, or strategic bolt-on acquisitions, acquisitions can accelerate growth while improving operational efficiency and strengthening market position.
Why Vendor Financing Matters for Business Sellers
Vendor financing can also create significant benefits for sellers.
A seller willing to provide a vendor note demonstrates confidence in both the quality of the business and its future prospects.
For buyers, this can increase confidence during negotiations and due diligence.
For lenders, it can serve as an additional signal that the seller believes in the business being sold.
After all, the seller typically knows the business better than anyone else involved in the transaction.
By participating in the transaction through a seller note, the seller sends a powerful message that they remain confident in the business even after ownership transfers to the buyer.
Risk Alignment and Buyer Protection
One of the most important benefits of vendor financing is the alignment it creates between buyer and seller.
Because part of the seller’s proceeds remain tied to the future performance of the business, both parties have an incentive to ensure a successful transition.
Properly structured vendor notes may also provide buyers with additional protection through indemnity provisions, set-off rights, and other contractual safeguards.
Where material misrepresentations, undisclosed liabilities, or previously unknown issues emerge after closing, the existence of a seller note can provide an additional mechanism through which buyers may seek protection, subject to the agreed transaction terms.
Examples may include:
- Undisclosed liabilities
- Hidden tax obligations
- Material misrepresentations
- Fraudulent financial reporting
- Undisclosed legal claims
- Previously unknown liens
As a result, vendor financing can act as both a financing tool and a risk-sharing mechanism.
Vendor Financing as an Additional Source of Acquisition Capital
For many business buyers, particularly first-time acquirers, obtaining financing is often one of the most challenging aspects of completing an acquisition.
Commercial lenders may not be willing to finance the entire purchase price. In other situations, buyers may wish to preserve capital for future growth initiatives, working capital requirements, or additional acquisitions.
Vendor financing can help bridge this funding gap.
By allowing a portion of the purchase price to be paid over time, transactions that might otherwise fail can often proceed successfully.
In many cases, vendor financing becomes the key component that transforms an otherwise unfinanceable transaction into a completed acquisition.
Seller Benefits: Faster Exits and Enhanced Transaction Certainty
Vendor financing can also help sellers achieve their objectives.
By offering a seller note, vendors may:
- Increase the pool of qualified buyers
- Improve deal completion rates
- Accelerate transaction timelines
- Generate additional interest income
- Potentially support higher valuations
- Create tax-planning opportunities through deferred proceeds
Most importantly, vendor financing can help overcome one of the biggest obstacles in any transaction: the funding gap between what sellers want and what buyers can reasonably finance.
What We Cover This Week
In this week’s FLIGHT 78910™ Blueprint, we examine how vendor financing is used across the SME acquisition market, particularly within transactions involving businesses generating approximately $1 million to $10 million EBITDA and enterprise values ranging from approximately $5 million to $50 million.
In our FLIGHT 78910™ SME Spotlight, we analyse how entrepreneur, investor, and author Codie Sanchez has popularised seller financing as a practical pathway for acquiring cash-flowing businesses and building wealth through acquisition.
Finally, our Strategic Takeaway and Conclusion bring together the most important lessons every entrepreneur, SME owner, and acquisition-minded business leader should understand before using vendor financing as part of a growth, acquisition, or succession strategy.
BLUEPRINT
The Smartest Business Buyers Don’t Use Their Own Money First
Vendor Financing (Seller Notes) for SME Growth & Acquisition
Target Audience
This week’s Blueprint is designed for SME owners, acquisition entrepreneurs, and growth-focused business leaders pursuing businesses typically generating $1 million to $10 million in EBITDA, with transaction values ranging from approximately $5 million to $50 million.
First-Time Business Buyers
Focus on:
- Reducing upfront cash equity requirements.
- Preserving working capital after closing.
- Aligning seller incentives with post-acquisition success.
- Reducing transition and operating risk.
Acquisition Entrepreneurs & Serial Acquirers
Focus on:
- Bridging valuation gaps.
- Preserving cash for future acquisitions.
- Scaling buy-and-build strategies.
- Strengthening returns on invested capital.
- Negotiating favourable seller note and subordination terms.
Executive Summary
One of the biggest challenges in SME acquisitions is the gap between what a business seller wants and what a bank is willing to finance.
For businesses generating between $1 million and $10 million EBITDA, commercial lenders typically provide senior debt of approximately 3.0x to 3.5x EBITDA due to collateral requirements, risk management policies, and banking regulations.
However, quality businesses often transact at 5.0x to 7.0x EBITDA, creating a funding gap that buyers must solve.
This is where Vendor Financing (Seller Financing) becomes valuable.
A seller note allows the seller to finance a portion of the purchase price, typically ranging from 10% to 30% of enterprise value, helping bridge the valuation gap while preserving buyer capital and reducing the need for external equity investors. For many successful acquisitions, vendor financing becomes the key component that transforms an otherwise unfinanceable opportunity into a completed transaction
Presentation Roadmap
- Slide 1: The Valuation & Capital Gap in SME Acquisitions
- Slide 2: What Is Vendor Financing and Where Does It Sit?
- Slide 3: How Vendor Financing Works: Rates, Terms & Structure
- Slide 4: Strategic Value: Why Buyers and Sellers Agree to Seller Notes
- Slide 5: Capital Stack Comparison: Bank Debt vs Vendor Financing vs Mezzanine Capital vs Private Equity
- Slide 6: Real-World SME Acquisition Case Study
- Slide 7: Risks, Bank Standstills & Common Pitfalls
- Slide 8: Key Takeaways & Vendor Financing Negotiation Checklist
Slide 1: The Valuation & Capital Gap in SME Acquisitions
Headline
How to Close the Gap Between Seller Price Expectations and Bank Lending Limits
Key Audience Insights
The Valuation Gap
Strong, cash-flowing SME businesses regularly trade between 5.0x and 7.0x EBITDA.
The Lending Ceiling
Most commercial lenders are generally prepared to provide between 3.0x and 3.5x EBITDA in senior debt.
The Equity Squeeze
Without vendor financing, buyers may be forced to:
- Invest significantly more personal capital.
- Bring in equity partners.
- Accept ownership dilution.
- Share future decision-making authority.
Speaker Notes
When acquiring a business generating $1 million to $10 million in EBITDA, there is often a difference between the seller’s valuation expectations and the amount a bank is willing to lend. Vendor financing is one of the most effective tools available for bridging that gap. By financing part of the purchase price, the seller becomes aligned with the future success of the business while helping the transaction move forward.
Slide 2: What Is Vendor Financing and Where Does It Sit?
Headline
Subordinated Acquisition Debt Provided Directly by the Seller
Core Concepts
Capital Stack Position
Vendor financing generally sits:
- Behind senior bank debt.
- Behind secured lenders.
- Ahead of common equity.
Typically Unsecured
Most seller notes are unsecured because senior lenders usually require first-ranking security over business assets.
Common Structures
Unsecured Promissory Note
A fixed seller note repaid over an agreed period, typically three to seven years.
Earn-Out Note
A payment structure linked to future business performance such as EBITDA, revenue, customer retention, or profit targets.
Standby Seller Note
A seller note where principal and interest payments are deferred until specified senior lender requirements have been satisfied.
Speaker Notes
Vendor financing is essentially deferred consideration. Rather than receiving 100% of the purchase price at closing, the seller agrees to receive part of the proceeds over time through a legally documented seller note paid from future business cash flows.
Slide 3: How Vendor Financing Works
Headline
Understanding Pricing, Terms & Structure
| Component | Typical Structure | How It Works | Buyer Benefit |
| Principal Slice | 10%-30% of Enterprise Value | Portion deferred to seller | Reduces equity required at closing |
| Interest Rate | 6%-10% | Fixed-rate seller debt | Lower cost than many alternative capital sources |
| Repayment Term | 3-7 Years | Monthly, quarterly, or balloon payments | Better alignment with cash flow |
| PIK Interest | 2%-4% | Interest accrues to principal | Preserves cash during transition |
Important Lending Terms
Subordination Agreement
A legal agreement establishing that senior lenders receive payment priority ahead of the seller note.
Bank Standstill
A provision allowing lenders to temporarily suspend seller note payments if banking covenants are breached.
Why It Matters
Good vendor financing structures help:
- Preserve working capital.
- Improve debt service coverage.
- Maintain operational flexibility.
- Increase transaction affordability
Slide 4: Strategic Value
Why Buyers Seek Vendor Financing
Seller Has Skin in the Game
The seller remains financially connected to the future success of the business.
Lower Cost of Capital
Vendor financing is often less expensive than:
- Private equity
- Minority investors
- Mezzanine lenders
Additional Protection
Seller notes can support:
- Set-off rights
- Indemnity claims
- Warranty protection
- Misrepresentation claims
Preserved Ownership
Buyers retain greater control while avoiding unnecessary equity dilution.
Why Sellers Accept Vendor Financing
- Supports Valuation Expectations
Seller notes may help bridge valuation gaps that would otherwise prevent a transaction.
- Tax Planning Opportunities
Installment receipts may create tax-planning benefits depending on local regulations.
- Additional Yield
Sellers receive interest income on deferred proceeds.
- Faster Transactions
Vendor financing can increase deal certainty and improve closing rates.
Slide 5: Capital Stack Comparison
Headline
Comparing Vendor Financing Against Other Acquisition Funding Sources
| Metric | Senior Bank Debt | Vendor Financing | Mezzanine Capital | Private Equity |
| Cost of Capital | 6%-9% | 6%-10% | 12%-18% | 20%-30%+ |
| Security Position | First-Lien | Subordinated | Second-Lien/Subordinated | Equity |
| Equity Dilution | None | None | Minimal | Significant |
| Seller Alignment | Low | High | Low | Low |
| Flexibility | Low | High | Moderate | Moderate |
| Control Retention | High | High | High | Reduced |
Strategic Observation
Vendor financing often provides one of the best balances between:
- Affordability
- Ownership retention
- Transaction flexibility
- Alignment of interests
- Capital preservation
Slide 6: Real-World SME Acquisition Case Study
Scenario
Acquisition Value
$15 million Enterprise Value
EBITDA
$3 million
Purchase Multiple
5.0x EBITDA
Example Deal Structure
Senior Bank Debt
$9 million (60%)
Vendor Financing
$3 million (20%)
Buyer Equity $3 million (20%
Without Vendor Financing
Buyer contribution:
$6 million equity (40%)
With Vendor Financing
Buyer contribution:
$3 million equity (20%)
Strategic Benefit
- Preserves buyer capital.
- Improves return on equity.
- Creates seller alignment.
- Supports smoother business transitions.
- Leaves capital available for future acquisitions and growth initiatives.
Slide 7: Risks, Bank Standstills & Common Pitfalls
Risk 1: Senior Debt Payment Block
The Risk
If financial covenants are breached, banks may suspend payments to the seller note.
Mitigation
Ensure blocked payments continue accruing interest without creating immediate default.
Risk 2: Excessive Debt Service
The Risk
Combined repayments can place pressure on business cash flow.
Mitigation
Negotiate:
- Interest-only periods.
- Deferred principal payments.
- Cash-flow-based repayment structures.
A 12-24 month transition period may allow the business to stabilise before full repayments commence.
Risk 3: Set-Off Disputes
The Risk
Disputes may arise if hidden liabilities or post-closing issues emerge.
Mitigation
Implement clearly documented:
- Escrow provisions
- Indemnity clauses
- Set-off rights
- Warranty protections
All documents should be reviewed by experienced M&A legal counsel.
Slide 8: Vendor Financing Negotiation Checklist
Vendor Financing Checklist
Target approximately 15%-25% of purchase price as seller financing where appropriate.
- Negotiate strong indemnity and set-off rights.
- Consider interest-only or PIK structures during the transition period.
- Ensure seller note terms align with lender requirements.
- Review all subordination agreements carefully.
- Stress-test repayment assumptions under downside scenarios.
- Conduct comprehensive financial, legal, operational, and commercial due diligence.
- Focus on preserving cash flow after closing rather than simply completing the transaction.
Blueprint Key Lesson
Vendor financing is not simply a financing tool.
For ambitious SME owners, acquisition entrepreneurs, and business leaders, it can become a strategic growth lever that helps acquire customers, cash flow, intellectual property, talent, market share, and competitive advantage while preserving capital for future expansion.
Used correctly, vendor financing can help accelerate the journey towards building stronger, growing, profitable 7-, 8-, 9-, and 10-figure businesses with sustainable competitive advantage.
Flight 78910™ SME Spotlight: Codie Sanchez
WATCH Video Feature: How She Made $50M Buying Boring Businesses | Codie Sanchez
Buying Cash Flow Instead of Building From Scratch
In this week’s FLIGHT 78910™ SME Spotlight, we examine how entrepreneur, investor, and author Codie Sanchez has helped popularise seller financing as a practical pathway for acquiring cash-flowing businesses.
While Sanchez primarily focuses on Main Street acquisitions, many of the principles behind seller financing, acquisition entrepreneurship, and capital-efficient growth can also be applied by ambitious SME owners seeking to build larger, more profitable businesses through acquisition.
Her approach centres on a simple but powerful idea:
Rather than spending years building customers, cash flow, systems, and market presence from scratch, acquire businesses that already possess those assets.
When combined with disciplined due diligence, effective deal structuring, and appropriate financing, acquisition-led growth can become a powerful route to building long-term wealth and enterprise value.
1. Core Thesis: Why the Seller May Be the Most Motivated Lender in the Transaction
One of Sanchez’s most widely discussed principles is that the seller can often become the most logical source of acquisition financing.
Her reasoning is straightforward.
Many Main Street business owners, particularly those approaching retirement, are not necessarily seeking a one-time windfall. Instead, they may be motivated by:
- Ongoing retirement income.
- Tax efficiency.
- Deal certainty.
- Business continuity.
- Confidence that their business will continue successfully after they leave.
As a result, seller financing can often create a structure that benefits both buyer and seller.
Why Sellers May Accept Vendor Financing
Tax Deferral Opportunities
Through an instalment sale structure, sellers may spread taxable gains across multiple years rather than recognising all proceeds immediately.
Additional Yield
Seller notes frequently generate interest income, often producing returns that may exceed those available from traditional cash deposits or low-risk investments.
Improved Transaction Certainty
Seller financing can help overcome funding gaps that might otherwise prevent a transaction from closing.
For many sellers, receiving slightly less cash upfront may be preferable to losing the transaction altogether.
2. Codie Sanchez’s Seller Financing Frameworks
Framework A: The Deal for Zero Model
One of Sanchez’s most recognised concepts is what she describes as a Deal for Zero strategy.
The objective is not necessarily acquiring a business with literally zero money down.
Instead, the goal is to minimise upfront equity while allowing the acquired business’s cash flow to support the acquisition.
Example Structure
Purchase Price / Enterprise Value: $500,000
Seller Financing (80%): $400,000
Buyer Down Payment (10%-20%): $50,000-$100,000
How It Works
Rather than contributing 100% of the purchase price personally, the buyer combines multiple funding sources.
Layer 1: Buyer Equity
Typically funded using:
- Personal cash
- SBA financing
- Equipment financing
- Small equity partners
Layer 2: Seller Financing
The seller finances approximately 80% of the purchase price through a seller note.
Layer 3: Business Cash Flow
Future profits generated by the business help service the seller note while continuing to create value for the buyer.
The underlying principle is simple:
Buy a business whose cash flow can comfortably support acquisition debt while still producing attractive returns for the owner.
Framework B: The RICH Acquisition Framework
Sanchez also promotes what she refers to as the RICH Framework for acquiring and growing small businesses.
R — Research
Target stable, recession-resistant businesses with established operating histories.
Examples include:
- HVAC businesses
- Plumbing companies
- Laundromats
- Car washes
- Service-based businesses
The focus is on predictable cash flow rather than exciting business concepts.
I — Invest
Maintain personal commitment to the transaction while avoiding excessive financial risk.
Seller financing can reduce the amount of personal capital required while maintaining alignment between buyer and seller.
C — Command
Build systems and management structures early.
The objective is to avoid purchasing another full-time job.
Where possible, empower a General Manager or operational leader to manage day-to-day operations.
H — Harness
Use the initial acquisition as a platform for future growth.
Additional acquisitions can expand:
- Customer bases
- Geographic reach
- Service offerings
- Market share
This creates the foundation for a buy-and-build strategy.
3. Financial Mechanics: How the Model Works
Consider a typical Main Street acquisition.
| Deal Metric | Example Value | Observation |
| Annual Cash Flow (SDE/EBITDA) | $150,000 | Stable recurring earnings |
| Valuation Multiple | 3.0x | Common Main Street range |
| Purchase Price | $450,000 | 3 x annual cash flow |
| Buyer Equity (15%) | $67,500 | Down payment |
| Seller Note (85%) | $382,500 | Financed over five years |
| Annual Debt Service | ~$93,000 | Paid from operating cash flow |
| Buyer Cash Flow | ~$57,000 | Remaining annual earnings |
Key Lesson
The attraction of seller financing is not simply acquiring a business with less cash.
The attraction is acquiring an asset whose cash flow helps fund its own purchase.
When executed correctly, this can create attractive cash-on-cash returns whilst preserving capital for future opportunities.
4. Key Deal Structures and Protective Clauses
One of the more practical aspects of Sanchez’s approach is her emphasis on structuring transactions to protect the buyer if operational performance deteriorates after closing.
Performance-Based Adjustments
Mechanism
Seller note terms may be adjusted if key business metrics deteriorate following acquisition.
Examples include:
- Revenue declines
- Customer losses
- Margin compression
- Employee departures
The goal is to create greater alignment between business performance and repayment obligations.
Set-Off Rights
Mechanism
The purchase agreement may allow the buyer to offset liabilities discovered after closing against future seller note payments.
Potential examples include:
- Undisclosed tax liabilities
- Hidden debts
- Material misrepresentations
- Breaches of warranties
This creates an additional layer of buyer protection.
Earn-Out and Standstill Structures
Mechanism
Elements of the transaction may be linked to future performance targets.
In other situations, repayment obligations may be temporarily deferred during transitional periods.
Examples include:
- Customer retention targets.
- Revenue milestones.
- Interest-only periods.
- Deferred principal payments.
These structures can help preserve working capital while reducing transaction risk.
5. Traditional Acquisition Financing vs Seller Financing
| Traditional Bank-Led Acquisition | Seller Financing Structure |
| Higher equity contribution required | Lower upfront capital required |
| Extensive lender underwriting | Greater deal flexibility |
| Seller exits immediately | Seller maintains alignment |
| Longer transaction timelines | Faster closing potential |
| Greater dependence on external approval | Greater negotiating flexibility |
Strategic Observation
The true advantage of seller financing is not simply reduced cash requirements.
The real value comes from creating alignment.
When buyers, sellers, and lenders all benefit from the future success of the business, transactions often become easier to structure and complete.
6. Key Risks & Practical Considerations
Despite its advantages, seller financing is not without risks.
Risk 1: Buying a Job Instead of a Business
A business may appear attractive on paper yet require substantial owner involvement.
If debt repayments consume most available cash flow and the owner must personally operate the business full-time, the acquisition may provide limited financial benefit.
Lesson
Acquire systems, not just income.
Risk 2: Seller Repossession Risk
If the buyer defaults on a seller note, the seller may have legal rights to enforce repayment, recover assets, or reclaim ownership depending on the transaction structure.
Lesson
Understand every repayment obligation before signing.
Risk 3: Hidden Business Weaknesses
Generous seller financing terms should not replace proper due diligence.
In some situations, sellers may be motivated to offer large seller notes because:
- Key customers are at risk.
- Equipment requires replacement.
- Industry conditions are deteriorating.
- Operational weaknesses exist.
Lesson
Trust the structure, but verify the business.
Comprehensive financial, legal, operational, and commercial due diligence remains essential.
Apply the Playbook →
Every Blueprint and Spotlight in this newsletter is a strategic lever.
Which one will you use to build a stronger, more competitive SME?
Strategic Takeaway
1. Vendor Financing: More Than a Financing Tool
Vendor financing is not simply a method of funding an acquisition. It is also a tool for aligning the interests of buyers, sellers, and, in many cases, lenders.
For first-time buyers in the Main Street market, seller financing should be approached carefully and strategically. Many business owners still expect to receive 100% of their sale proceeds at closing and may initially resist the idea of financing part of the transaction themselves.
As a result, buyers may achieve better outcomes by first building trust, understanding the seller’s motivations, and presenting vendor financing as a collaborative solution rather than an aggressive opening demand. Every deal is different, and buyers should decide early whether seller financing forms part of their acquisition strategy, how much seller participation is required, and how best to introduce the concept.
In the lower-middle market and mid-market, vendor financing is more widely understood and often forms part of acquisition discussions from the outset. In these situations, seller financing may be introduced early within the Letter of Intent (LOI) as a deal-structuring tool designed to bridge funding gaps, align incentives, and improve transaction certainty.
2. Earn-Out Versus Vendor Financing
Buyers should avoid treating earn-outs and vendor financing as interchangeable concepts.
A seller note is generally a contractual debt obligation for an agreed amount that is payable according to predetermined terms. The amount owed is typically established at closing and remains payable unless otherwise modified by the acquisition agreement.
An earn-out, by contrast, is contingent consideration that only becomes payable if defined performance targets are achieved after closing. While both structures defer payment, they serve different purposes and address different risks.
Vendor financing is primarily a financing and risk-alignment mechanism. Earn-outs are primarily performance-based incentives used to address uncertainty regarding future business performance.
Where a business relies heavily on the seller’s personal relationships, customer network, or ongoing involvement, earn-outs may complement vendor financing by helping ensure a successful transition.
3. How Vendor Financing Can Help the Banker
Where external debt is required, a seller willing to provide vendor financing may strengthen a bank’s confidence in the transaction.
From a lender’s perspective, the seller is effectively demonstrating confidence in both the quality of the business and the capabilities of the buyer. After all, the seller typically knows the business better than anyone else involved in the transaction.
As a result, seller participation can help create alignment between the buyer, seller, and lender, potentially improving the lender’s assessment of transaction risk.
That said, the importance of seller financing varies by market and financing environment. In some jurisdictions, government-backed lending programmes, such as SBA loans in the United States, may already provide substantial leverage and reduce the need for large seller notes.
Ultimately, successful acquisitions depend on selecting the right financing structure for the specific deal, understanding lender requirements, and ensuring all parties remain aligned throughout the transaction process.
Conclusion
Vendor financing remains one of the most powerful and flexible tools available to business buyers and sellers.
For buyers, it can bridge funding gaps, reduce upfront capital requirements, improve alignment with sellers, and provide valuable protection through carefully structured legal agreements and seller participation.
For sellers, it can help close valuation gaps, attract a broader buyer pool, increase transaction certainty, generate additional yield through interest income, and create potential tax-planning opportunities through deferred payments.
However, the true value of vendor financing extends beyond the funding itself.
Business acquisitions involve significant amounts of capital, long-term commitments, and inherently illiquid assets. The seller almost always possesses more knowledge about the business than the buyer. For this reason, buyers should seek to structure transactions that appropriately balance risk, align incentives, and provide protection if unexpected issues emerge after closing.
Equally important is assembling the right team of professionals.
Acquisitions should be supported by qualified accountants, lawyers, M&A advisers, financial professionals, and industry specialists where appropriate. Professional advice is often far less expensive than correcting the consequences of a poorly structured acquisition after completion.
While artificial intelligence can be an excellent research and learning tool, it is not a substitute for qualified legal, tax, accounting, or mergers-and-acquisitions advice.
For sellers, understanding the importance of timing may be just as important as understanding valuation.
Many owners reach a point where they are ready to move on, retire, pursue new opportunities, or simply reduce the demands of business ownership. When market conditions, personal circumstances, and buyer demand align, delaying a sale can sometimes create unnecessary risk.
As many deal professionals say:
“Time kills deals.”
Waiting too long can lead to changing economic conditions, lower valuations, reduced buyer demand, or missed opportunities to achieve a successful exit.
For sellers seeking to maximise transaction certainty and attract the right buyer, vendor financing can become an important part of the solution. Just as financing plays a critical role in facilitating major purchases such as property, equipment, and vehicles, seller financing can help unlock business acquisitions that might not otherwise occur.
Our FLIGHT 78910™ SME Spotlight this week highlighted the acquisition strategies popularised by Codie Sanchez. Her central message reinforces a broader principle: acquiring an existing cash-flowing business can, in many situations, be a faster and less risky route to business ownership than building entirely from scratch.
The same principle can be seen throughout business history. While not specifically driven by vendor financing, Bernard Arnault’s creation and expansion of LVMH demonstrates the power of acquisition-led growth. Through a disciplined acquisition strategy, LVMH evolved into one of the world’s largest luxury groups by acquiring and developing premium brands across multiple sectors.
The lesson is not that every acquisition will succeed. Rather, it is that acquisitions, when executed correctly, can become a powerful strategic growth lever.
Vendor financing, combined with proper due diligence, professional advice, disciplined execution, and thoughtful deal structuring, can help SME owners, entrepreneurs, and acquisition-minded business leaders acquire customers, cash flow, intellectual property, market share, talent, and competitive advantage far faster than may be possible through organic growth alone.
Above all, every acquisition should be approached with the appropriate expertise, preparation, and understanding of the market involved.
Done correctly, vendor financing can become far more than a funding mechanism. It can become a strategic tool that helps build stronger, growing, profitable 7-, 8-, 9-, and 10-figure businesses with sustainable competitive advantage.
Continue Your Growth Journey →
If this edition has challenged your thinking or highlighted opportunities within your own business, explore our collection of practical frameworks, business tools and strategic growth resources designed to help SME owners build stronger, more profitable and more valuable businesses.
Know a business owner, entrepreneur or SME leader who would benefit from these insights? Please share this edition with them.
References
Subscribe for weekly strategy your fellow SMEs are already using to strengthen their competitive edge.
Related Posts:
- How to Buy a Business Without Millions: The SMB Acquisition Funding Blueprint – The2015B Group
- Equity Financing for SMBs: How to Raise Capital Without Losing Control – The2015B Group
- From £150K to £525M: What SMB Owners Can Learn About Growth, Debt, Mezzanine Finance & Private Equity from Tamara Mellon – The2015B Group
Until next week—
Set bold strategy. Set big targets. Take massive action. Measure what matters.
About the Author
Aby Rufus
Business Investor Strategy Expert Entrepreneur with an MBA in Strategic Planning—offering billion-dollar strategic solutions for SMEs.