
How Smart Business Owners Use Debt Financing to Grow, Scale and Acquire Businesses
Hi, I’m Aby
Welcome to The Strategic Billion Dollar PEN, your weekly business strategy newsletter designed to equip SME business owners and entrepreneurs with the clarity, confidence, and competitive edge to grow and scale with purpose—successfully.
Want a smarter, stronger business?
Then it’s time to turn strategy into your superpower—the fuel behind every bold move, every sharp pivot, and every win that leaves your competition scrambling.
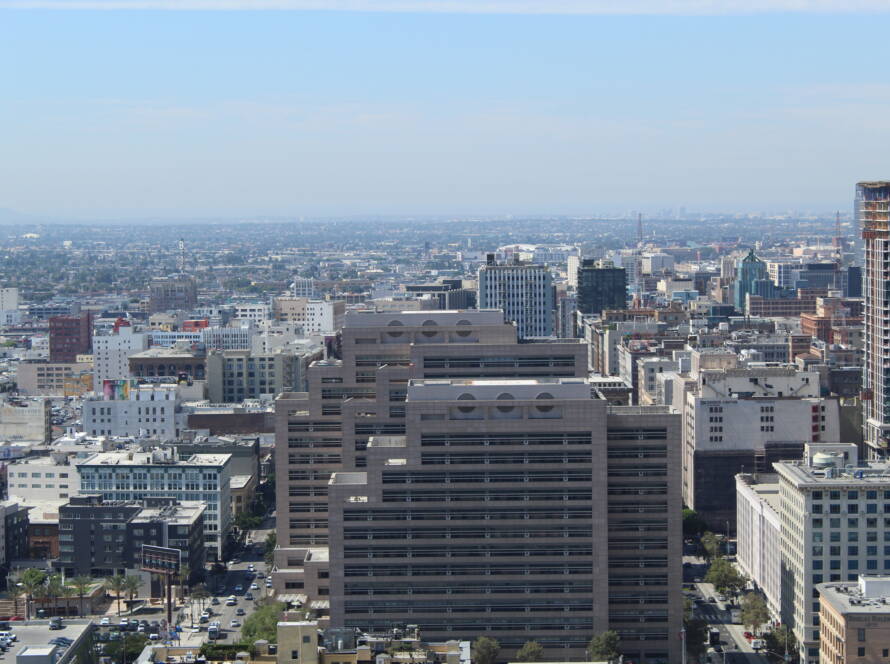
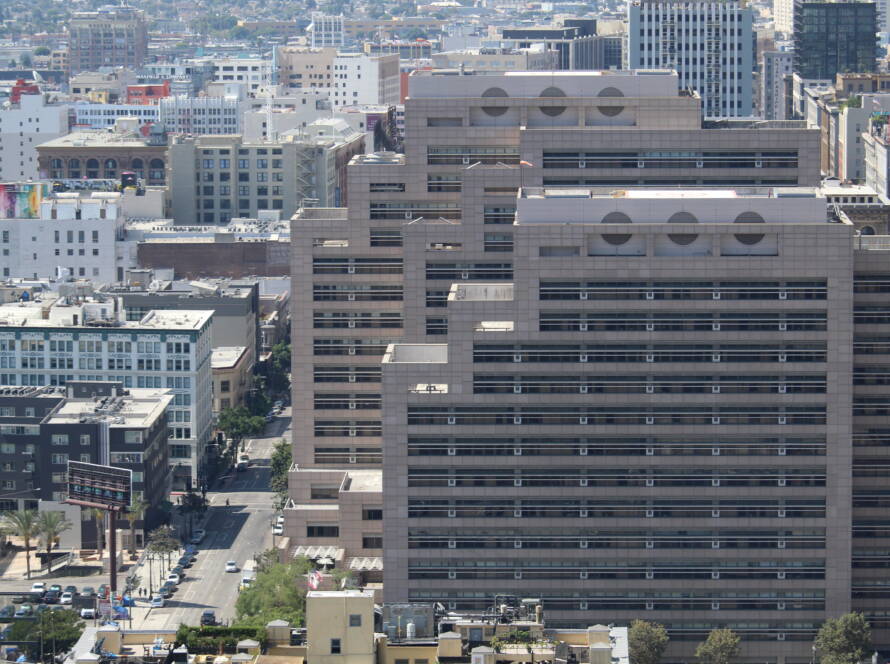
Our HERO image this week depicts A modern commercial skyline featuring a dominant central tower surrounded by supporting structures, symbolising how strategic funding, financial leverage, and capital allocation enable businesses to build scale, resilience, and sustainable growth over time.
The Wrong Debt Can Destroy Your Business. The Right Debt Can Build It.
Introduction
Debt financing remains one of the most powerful business-growth tools available to companies seeking expansion, working capital, capital investment or acquisition opportunities. Whether used by multinational corporations, mid-market firms or small and medium-sized enterprises (SMEs), debt can provide access to the capital needed to grow operations, strengthen competitive positioning and create long-term enterprise value.
This week, we explore how businesses use debt financing strategically, the situations where debt can create value and the risks business owners must understand before borrowing. We examine how debt supports business growth, mergers and acquisitions, capital investment and working-capital management across different stages of the business lifecycle.
Best Uses of Debt Financing in Large Businesses
1. Funding High-ROI Capital Expenditure (CapEx)
The Concept
Using long-term debt to finance machinery, facilities, technology and infrastructure assets that generate predictable cash flows and returns exceeding the cost of capital.
Key Insight
Debt creates value when returns on invested capital comfortably exceed the after-tax cost of borrowing.
2. Accretive Mergers and Acquisitions (M&A)
The Concept
Using debt to finance acquisitions where expected synergies, efficiencies and future cash flows support debt repayment.
Key Insight
Debt financing can preserve shareholder ownership while supporting growth through acquisition, provided the combined business generates sufficient cash flow to service the debt.
3. Optimising Working Capital and Cash Conversion Cycles
The Concept
Using revolving credit facilities and short-term financing to manage inventory purchases and receivables gaps.
Key Insight
Debt can improve liquidity and operational flexibility without tying up large amounts of equity capital.
4. Countercyclical Strategic Investments
The Concept
Maintaining prudent leverage so businesses have borrowing capacity available during economic downturns.
Key Insight
Companies with strong balance sheets often acquire distressed assets, gain market share and accelerate growth during periods when competitors face financial constraints.
Small and Medium Business Debt Financing
While large corporations often have dedicated finance teams and sophisticated capital-allocation strategies, small and medium-sized businesses must make financing decisions with significantly fewer resources and less margin for error.
The ability to understand and use debt financing effectively can make the difference between business growth and business stagnation.
Many SMBs fail because they take on debt that exceeds their repayment capacity. Conversely, many otherwise successful businesses remain smaller than their potential because they lack access to the capital needed to invest in people, systems, inventory, marketing, technology or expansion opportunities.
In some cases, business owners become trapped in a cycle where debt repayments consume cash flow that could otherwise be reinvested into growth. This can lead to limited hiring capacity, operational strain and slower business development.
Understanding debt financing is therefore not simply about securing funding. It is about securing the right funding, for the right purpose, under the right terms.
To make better financing decisions, SMB owners should understand the following key principles:
1. Understanding Different Types of Business Debt
Business owners should understand the various forms of business financing available and the role each serves within a growth strategy. Financing options such as lines of credit, term loans, subordinated debt, convertible debt, demand loans and mezzanine financing all serve different purposes depending on cash-flow requirements, growth objectives and acquisition plans.
Selecting the correct financing structure can improve business flexibility, support expansion and reduce financial stress.
2. Understanding Lender Requirements, Characteristics and Debt Features
Not all lenders operate under the same criteria. Business owners should understand lender expectations relating to interest rates, APR, approval processes, risk assessments, loan structures and repayment obligations.
Traditional banks, digital lenders, specialised debt providers and alternative financing sources each have unique advantages and disadvantages. Understanding these differences enables business owners to make more informed financing decisions.
3. Understanding How Banks Evaluate Borrowers
Banks assess multiple factors before approving debt financing, including business cash flow, collateral availability, guarantee requirements, debt-service coverage ratios and debt-to-equity ratios.
Because SMEs are often considered higher-risk borrowers, understanding these requirements can significantly improve financing readiness and increase the chances of securing funding under favourable terms.
4. Understanding the 5 Cs of Lending
One of the most widely used lending frameworks is the 5 Cs of Credit:
- Character
- Capacity
- Capital
- Collateral
- Conditions
Understanding how lenders apply these principles can help business owners identify suitable lenders, strengthen loan applications and improve access to capital.
In our Blueprint this week, we explore the most effective uses of debt financing for founders, SMBs business owner and entrepreneurs while examining the key principles required to obtain and use debt responsibly.
In our FLIGHT 78910™ SME Spotlight, we analyse the entrepreneurial journey of Elina Wang, founder of ESW Beauty, who launched her business using a $25,000 SBA loan. We examine her experience through the lens of SME financing and identify practical lessons that business owners can apply when using debt to support growth.
Finally, our Strategic Takeaway and Conclusion bring together the most important debt-financing lessons every entrepreneur, business owner and SME leader should understand before pursuing business funding, business growth or acquisition opportunities.
BLUEPRINT
The Debt Financing Playbook Every SME Owner Should Understand
To help business owners better understand the opportunities and risks associated with debt financing, the following insights are presented using an SME-adapted interpretation of corporate finance principles commonly applied by leading advisory firms and institutional investors.
While large enterprises focus on optimising their weighted average cost of capital (WACC), managing complex capital structures and accessing public debt markets, SMEs operate under very different conditions. Small and medium-sized businesses typically face more volatile cash flows, less asset liquidity and higher borrowing costs, making debt financing decisions significantly more consequential.
As a result, SME owners must focus less on financial engineering and more on practical considerations such as cash-flow management, revenue generation, liquidity preservation and sustainable growth.
For SMEs, the most effective uses of debt financing are typically those that support immediate cash conversion, revenue growth, operational efficiency and business expansion while avoiding unnecessary equity dilution.
Best Use Cases for Debt Financing in SMEs
1. Bridging the Cash Conversion Cycle (Working Capital & Inventory Build-Up)
The Use Case
Using a revolving line of credit, working-capital facility or invoice financing solution to purchase inventory, raw materials or fulfil large customer orders before customer payments are received.
Why It Works for SMEs
Unlike large corporations that often have substantial cash reserves, SMEs can experience significant cash-flow pressure even when they are profitable. Capital tied up in inventory or accounts receivable can create liquidity constraints that restrict growth.
Appropriately structured debt can bridge this timing gap, helping businesses maintain operations, serve customers and capture growth opportunities without disrupting cash flow.
Key Insight
Profits do not pay suppliers. Cash does. Debt used to shorten the cash conversion cycle can protect business continuity and support growth.
2. Purchasing High-Velocity Revenue-Generating Equipment
The Use Case
Using equipment finance, leasing arrangements or term loans to acquire machinery, technology, specialised tools or software systems that directly increase productivity, efficiency or revenue generation.
Why It Works for SMEs
The asset often serves as collateral, reducing lender risk while enabling the business to preserve cash reserves.
When structured correctly, the revenue or cost savings generated by the equipment should exceed the monthly financing costs, creating positive cash-flow impact and improving overall business performance.
Key Insight
Debt becomes a strategic asset when the investment generates a return greater than the cost of borrowing.
3. Strategic Inventory Pre-Purchasing and Supplier Discounts
The Use Case
Using short-term financing to purchase inventory in larger quantities, secure supplier discounts or lock in favourable pricing before peak trading periods.
Why It Works for SMEs
Many suppliers offer significant discounts for bulk purchases. If the financial benefit of the discount exceeds the cost of the financing, debt can immediately improve gross margins and profitability.
In addition, businesses may gain protection against future price increases, supply shortages or seasonal demand fluctuations.
Key Insight
When savings generated exceed borrowing costs, debt can directly improve profit margins.
4. Geographic Expansion or Opening an Additional Revenue Unit
The Use Case
Financing the expansion of an already proven business model into a new market, location or channel.
Examples may include opening a second location, launching a new service division, entering a new region or expanding distribution capabilities.
Why It Works for SMEs
Because the underlying business model has already demonstrated commercial viability, the risk profile is often lower than funding an entirely untested concept.
Debt financing allows founders to retain ownership and avoid shareholder dilution that may accompany equity-based funding.
Key Insight
When expansion is built on a proven operating model, debt can accelerate growth while preserving control and ownership.
Strategic Guardrails for SME Borrowers
Understanding when to borrow is just as important as understanding how to borrow.
1. Avoid Over-Leveraging Fixed Operating Costs
Large corporations may be able to withstand prolonged economic downturns through diversified revenue streams and access to multiple financing sources.
Most SMEs do not enjoy the same flexibility.
Debt repayments should remain comfortably manageable under conservative cash-flow assumptions, not just during periods of strong performance.
Guiding Principle
Always structure debt based on expected downside scenarios, not best-case forecasts.
2. Match Debt Maturity to Asset Life
One of the most common financing mistakes among SMEs is using short-term expensive financing to fund long-term assets.
For example, using merchant cash advances or short-term facilities to purchase long-life assets such as equipment, vehicles or property can create unnecessary pressure on cash flow.
A more effective approach is to align the repayment period with the expected economic life of the asset being financed.
Guiding Principle
- Short-term debt for working capital.
- Medium-term debt for equipment and technology.
- Long-term debt for expansion projects and property investments.
Flight 78910™ SME Spotlight: Elina Wang
WATCH Video Feature: From Broke College Student to $20M Brand in 10,000 Stores | ESW Beauty
IElina Wang: From Broke College Student to a $20 Million Brand in 10,000 Retail Locations
Based on the Foundr interview with Elina Wang, co-founder of ESW Beauty, this week’s SME Spotlight provides a real-world example of the debt-financing principles explored throughout this edition.
Like many entrepreneurs, Wang did not begin her journey with significant capital, investors or institutional backing. Instead, she leveraged a relatively modest loan to launch her business, fund initial inventory production and bring her product to market.
Today, ESW Beauty products are distributed across more than 10,000 retail locations, demonstrating how strategic financing, disciplined capital management and strong execution can help transform a simple business idea into a nationally recognised brand.
Her experience provides several valuable lessons for business owners considering debt financing as a tool for growth.
Key Takeaways from the ESW Beauty Case Study
1. The Catalyst: A Right-Sized $25,000 Loan
The Move
Starting shortly after graduating from college and with limited personal capital, Wang utilised a modest $25,000 SBA-backed loan to fund initial product formulation, packaging development and her first inventory production run.
The Lesson
Rather than pursuing large amounts of venture capital or relying on expensive short-term financing, she secured an amount that was closely aligned with the actual needs of the business at that stage of growth.
By matching the size of the financing to the opportunity, the business maintained manageable monthly repayments while reducing financial pressure during its earliest stages.
Flight78910™ Insight
Successful entrepreneurs often focus less on borrowing the maximum amount available and more on borrowing the amount required to achieve a specific business objective.
2. Non-Dilutive Growth and Equity Preservation
The Move
By using debt financing instead of selling ownership stakes to outside investors, the founders retained control of their business and preserved their equity position.
The Lesson
As ESW Beauty expanded into thousands of retail locations and scaled into a multi-million-dollar business, the founders benefited from the long-term value created by the company without giving away significant ownership at an early stage.
For many entrepreneurs, preserving ownership during the early years can become one of the most valuable financial decisions they make.
Flight78910™ Insight Debt financing can be an effective alternative to equity financing when the business
3. Strong Unit Economics and Sustainable Debt Service
The Move
ESW Beauty operated in a category with attractive gross margins, enabling the company to generate meaningful revenue from relatively modest inventory investments.
The Lesson
The products generated sufficient cash flow to comfortably cover loan repayments while supporting ongoing business growth.
This illustrates an important principle of debt financing: revenue generated from the financed asset or inventory should exceed the cost of the debt used to acquire it.
When this relationship remains positive, debt can become a growth accelerator rather than a financial burden.
Flight78910™ Insight
Businesses should focus on ensuring that financed assets, inventory or growth initiatives produce cash-flow returns that comfortably exceed borrowing costs.
Strategic Lessons for SME Borrowers
Leverage Should Be a Growth Spark, Not a Lifeline
The purpose of debt financing should be to fund assets, inventory, equipment or initiatives that generate future revenue.
In the case of ESW Beauty, debt was used to bridge the gap between manufacturing products and generating sales revenue. The financing supported growth rather than compensating for a weak business model.
Lesson for SME Owners
Borrow to create value, not simply to cover recurring operational shortfalls.
Combine Bootstrapping Discipline with Smart Leverage
One of the most compelling aspects of the ESW Beauty story is the balance between disciplined entrepreneurship and strategic financing.
The business did not rely on constant fundraising or excessive borrowing. Instead, it combined prudent financial management with carefully selected financing solutions that supported growth objectives.
This approach enabled the founders to maintain control, preserve ownership and build a business that scaled into thousands of retail locations.
Lesson for SME Owners
Debt works best when supported by strong financial discipline, healthy cash flow and a clear growth strategy.
Apply the Playbook →
Every Blueprint and Spotlight in this newsletter is a strategic lever.
Which one will you use to build a stronger, more competitive SME?
Strategic Takeaway
The goal for small and medium-sized business owners and entrepreneurs is not simply to obtain debt financing.
The goal is to become the type of business owner and steward of capital that lenders, investors and financial institutions are comfortable backing over the long term.
Access to funding is rarely a single event. It is the result of establishing sound financial policies, maintaining strong cash-flow discipline and developing credibility with lenders over time.
The following principles can help business owners improve their financing readiness and strengthen their access to capital.
1. Establish a Clear Financial Policy
Every business owner should determine how debt will be used within their business before financing is needed.
This begins by deciding whether the business will operate under a more conservative or aggressive financing strategy and developing a disciplined approach to capital allocation.
A financial policy acts as a framework for making borrowing decisions and helps ensure that debt is used intentionally rather than reactively.
Key Question
Will debt be used primarily for working capital, growth, acquisitions, equipment purchases or strategic expansion opportunities?
Businesses that answer this question before they need financing are often better positioned than those who seek funding under pressure.
2. Identify and Understand Your Preferred Lenders
Different lenders have different risk appetites, lending criteria and financing objectives.
Business owners should identify the institutions most aligned with their financing needs and invest time in understanding how those lenders make decisions.
For example, traditional banks remain one of the most attractive sources of lower-cost capital for many SMEs. However, banks are inherently risk-averse institutions.
As many experienced lenders acknowledge:
Banks are not primarily in the business of issuing loans. They are in the business of generating returns while managing risk. As a result, a business with weak financial performance, inconsistent cash flow or insufficient assets may struggle to obtain financing.
Understanding this reality enables business owners to prepare long before capital is required.
Build Banking Relationships Before You Need Funding
One often-overlooked strategy is relationship building.
Rather than approaching lenders only when money is required, successful business owners cultivate relationships with banking professionals and SME-focused lenders throughout the year.
Regular conversations help business owners:
- Understand changing lending conditions.
- Learn what lenders currently prioritise.
- Identify emerging financing opportunities.
- Become known and trusted by potential lenders.
The objective is simple: build relationships before you need capital.
Understand Lending Cycles
Business owners should also recognise that lender behaviour changes throughout the year.
Some lending institutions may become more active during certain periods as they seek to achieve lending targets, while others may tighten requirements in response to economic conditions.
Understanding these lending cycles can improve timing and increase the likelihood of securing favourable financing terms when opportunities arise.
3. Master Cash Flow Management
No factor is more important to a lender than cash flow.
Regardless of the type of financing sought, lenders ultimately want confidence that the business can comfortably service its debt obligations while continuing to operate successfully.
This makes cash-flow management one of the most important disciplines for any business owner.
A robust cash-flow policy should include:
- Clear visibility into operating cash flow.
- Consistently healthy gross margins.
- Strong working-capital management.
- Regular financial reporting and forecasting.
- Adequate liquidity reserves.
Businesses with predictable cash flows are generally viewed as lower-risk borrowers and therefore gain greater access to financing options.
Flight78910™ Insight
A lender is often lending against future cash flow more than current assets.
4. Stress-Test Every Financing Decision
Before taking on any debt, business owners should assess their ability to service repayments under less favourable circumstances.
One practical approach is to implement sensitivity analysis and scenario planning.
Consider questions such as:
- What happens if sales decline by 30%?
- What happens if sales decline by 50%?
- What happens if a key customer is lost?
- What happens if inventory costs increase significantly?
- Can debt obligations still be comfortably met?
The most resilient businesses plan for adverse conditions before they occur.
Debt should be structured around downside scenarios rather than best-case growth assumptions.
The Ultimate Lesson
The most reliable way to secure consistent access to capital is to become financially disciplined, financing-ready and highly credible in the eyes of lenders.
Business owners who understand cash flow, maintain strong financial controls, build lender relationships and use debt strategically will often find that financing opportunities become easier to access over time.
Debt financing should never be viewed as a shortcut.
It should be viewed as a strategic tool that, when used responsibly, can accelerate growth, preserve ownership and create long-term enterprise value.
Conclusion
This week, we explored debt financing and the key principles business owners, entrepreneurs and SME leaders must understand to successfully access and utilise debt financing for business acquisitions, business growth and day-to-day operations.
Whether operating a large enterprise or a small and medium-sized business, debt should never be used simply for the sake of leverage. Instead, debt should serve a clear strategic purpose, support long-term business objectives, preserve ownership where appropriate and contribute positively to overall business performance.
As we highlighted throughout this edition, and particularly in our discussion on Why Understanding Debt Financing Matters for SME Owners, the consequences of poorly structured debt can be significant. Businesses can become restricted by cash-flow pressures, unable to invest in growth opportunities and, in extreme cases, unable to sustain operations.
The goal is not to avoid debt altogether. The goal is to use debt intelligently.
Our FLIGHT 78910™ SME Spotlight illustrated this principle through the story of Elina Wang and ESW Beauty. Rather than seeking excessive financing, she matched the size of the debt to the specific needs of the business. By keeping debt obligations manageable and aligned with inventory requirements, she was able to focus on growth, preserve flexibility and avoid placing unnecessary strain on the company’s cash flow.
Her experience demonstrates the value of a conservative and disciplined financial policy, particularly during the early stages of business development.
For SME owners and entrepreneurs, one of the most important decisions is determining how debt will fit within the overall financing strategy of the business. Whether a business adopts a conservative, balanced or more aggressive financing approach, that decision should be made deliberately and supported by clear financial policies, consistent reporting and disciplined execution.
Once a financing philosophy has been established, it becomes easier to:
- Recruit financial talent aligned with the business’s objectives.
- Implement appropriate financial controls and reporting systems.
- Monitor key performance indicators and dashboard metrics.
- Identify margin weaknesses and operational inefficiencies.
- Make informed pricing adjustments to improve cash flow.
- Adapt business models when market conditions change.
- Evaluate debt-financing opportunities with greater confidence and discipline.
These business levers can often determine whether a company remains financially resilient or struggles under the weight of debt obligations.
Ultimately, access to capital is not simply about finding lenders. It is about becoming a business that lenders want to finance. Business owners who understand debt financing, master cash-flow management, build relationships with lenders and maintain sound financial discipline position themselves to access funding when opportunities arise.
References
Subscribe for weekly strategy your fellow SMEs are already using to strengthen their competitive edge.
Related Posts:
- How to Buy a Business Without Millions: The SMB Acquisition Funding Blueprint – The2015B Group
- Equity Financing for SMBs: How to Raise Capital Without Losing Control – The2015B Group
Until next week—
Set bold strategy. Set big targets. Take massive action. Measure what matters.
About the Author
Aby Rufus
Business Investor Strategy Expert Entrepreneur with an MBA in Strategic Planning—offering billion-dollar strategic solutions for SMEs.